Chapter 03 · Section 3.1
Binomial Pricing Question 6
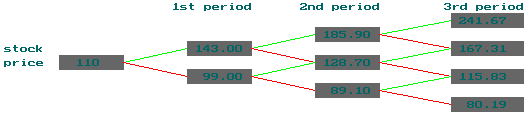
The diagram of the stock price evolution develops in this direction ------>
<--------The diagram of the call value evolution develops in this direction
Stock XYZ costs 110. We shall determine the price of the call with an exercise price of 100 knowing that: the probability that the stock rises or falls is the same (0.5); the risk free interest rate is 10%.
If the 3rd period corresponds to the expiration of the option, the value which would be held by the call at expiration, given the different possible stock prices, is: