Chapter 03 · Section 3.1
Explanation of calculation
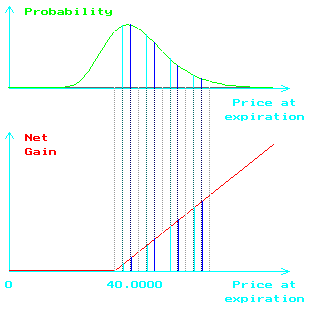 One can see that it is possible to calculate the theoretical value of
a european option if one knows:
The probability distribution associated with each possible stock price at expiration. The option's strike price and therefore the gain associated with each possible stock price at expiration.
The two graphs illustrate the calculation of the premium of a call with a strike price of 40 when the underlying's value is 45: Each possible gain is weighted with its corresponding probabillity and summed to give the fair value.