Chapter 05 · Section 5.1
Delta - Call
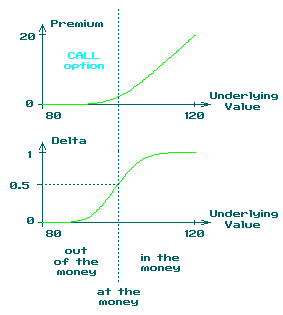 The top picture represents a call option 30 days before expiration with an exercise price of 100, the bottom graphic represents the delta profile of the call.
The delta is the slope of the line representing the option premium as a function of the price of the underling.
The more a call is out-of-the-money, the closer the delta is to zero. The more a call is in-the-money, the closer the delta is to 1.
When the call is at-the-money, the delta is 0.5.
← PrevNext →