Chapter 05 · Section 5.1
The effect of the price of the underlying
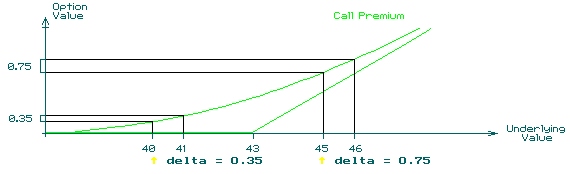 The price of the underlying is only one of many factors which affect the premium of an option. In examining the effect of the price of the underlying on the premium, one must assume that all other factors, such as volatility and time, remain constant. The result can be presented graphically: The green curve represents the price of a call as a function of the price of the underlying. It illustrates that if the price of the underlying increases from 40 to 41, the call premium increases 35 cents, if all other factors affecting the premium remain unchanged.
The relationship between a change in the price of the underlying and a change in the premium is called the delta. Graphically, the delta corresponds to the slope of (the tangent to) the curve, and therefore, it is not constant.The delta of this call is 0.35 when the price of the underlying is 40. It is 0.75 when the price of the underlying is 45. To determine the change in delta brought about by a change in the price of the underlying, one uses the gamma.