Chapter 03 · Section 3.1
Binomial Pricing Question 1
Stock XYZ costs 110. There is a call option and a put option listed on this stock, both with an exercise price of 100. It is equally probable that the stock could go up to a level of 143 or down to a level of 99.
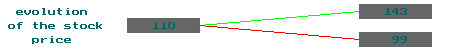
Assume that the option expires at the end of the first period and that stock prices do indeed rise instead of fall. What is the value held by the call at the end of the first period? Please enter the corresponding figure.
 a) 0
 b) -1/42
 c)
 d)
 (Click here for help)