Chapter 03 · Section 3.1
Binomial Pricing Question 2
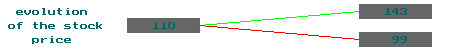
Stock XYZ costs 110. There is a call option and a put option listed on this stock, both with an exercise price of 100. There is a 50% probability that the stock could go up to a level of 143 and a 50% probability that the stock could go down to a level of 99. The risk free interest rate is 10%. Given these hypotheses, what should be the current value of the call?
 a) -21.50
 b) -1
 c) 24
 d) 1/19.53
 e) +19.54
 f) 0
 You have the same probability that the value of the call at the end of the next period will be 43 or 0. Without taking into account the effect of a 10% interest rate, the calculation is: (0.5 x 43) + (0.5 x 0) = 21.50
You must then "discount" back the price to its present value in order to account for the 10% interest rate effective between the current date and the end of the first period. *note: I added the above help as I thought the explanation was unclear.
You must divide the un-discounted value of the call by a factor of (1 + 10%). The present value of the call is 21.50 / (1 + 10%).