Chapter 03 · Section 3.1
Binomial Pricing Question 3
Stock XYZ costs 110. There is a call option and a put option listed on this stock, both with an exercise price of 100. There is a 50% probability that the stock could go up to a level of 143 and a 50% probability that the stock could go down to a level of 99. The risk free interest rate is 10%.
evolution of the stock price
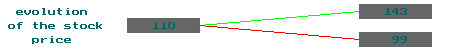
What will be the value of the put given these hypotheses?
 a) -1
No. No. The value of the put is not negative, at the worst it is without value. b) -0
 c) -0.50
 d) -0.00/0.44
 e) -0.46/99999
 f) +0.45
 (Click here for help)