Chapter 06 · Section 6.1
Long Put
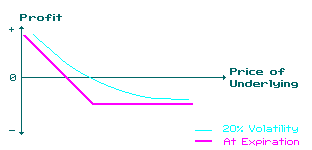
Now that we know that the call buyer is willing to pay more money for a option on a stock with increased volatility and the writer is able to demand a higher premium. What effect does volatility have on put options?
Consider a change in volatility from 20% to 25%. The profit potential of a put holder is?
 a) unchanged.
 b) increased.
 c) decreased.
 A volatility of 20% means that on average the price of the underlying has varied as much as 20% in a given period of time.
With an increase in the volatility from 20-25% the chances that the put will be in the money are increased as a result of the increased variation in the underlying stock.