Chapter 03 · Section 3.1
Discrete option value calculation
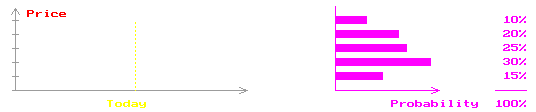
Imagine that stock XXX can only take on the values of 20, 40, 60, 80 and 100. Suppose that for the given expiration, the probabilities associated with each of these prices are known and correspond with the values indicated in the graph. For simplicity, assume that the interest rate is zero.
What will be the price of a european call with an exercise price of 60?
 c) +8
Yes. The call value corresponds to the average gain, that is to the sum of all the possible gain multiplied by their associated probabilities.Continue
 d) --99999999/99999999
 a) -1000
 b) -56
 (Click here for help)