Chapter 03 · Section 3.1
Discrete option value calculation
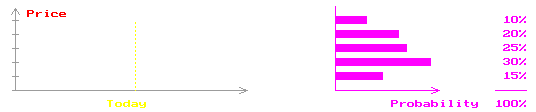
Imagine that stock XXX can only take on the values of 20, 40, 60, 80 and 100. Suppose that for the given expiration, the probabilities associated with each of these prices are known and correspond with the values indicated in the graph. For simplicity, assume that the interest rate is zero.
What will be the price of a european call with an exercise price of 60?
 a) -1000
 b) -56
 c) +8
 d) --99999999/99999999
 Multiply the profit which the call holder can realize for each possible price by its associated probability.
One must therefore find the prices that actually mean a profit for the call holder, taking into account that - in this example - the only possible prices for the stock are 20, 40, 60, 80 and 100.